 Russell Andrews
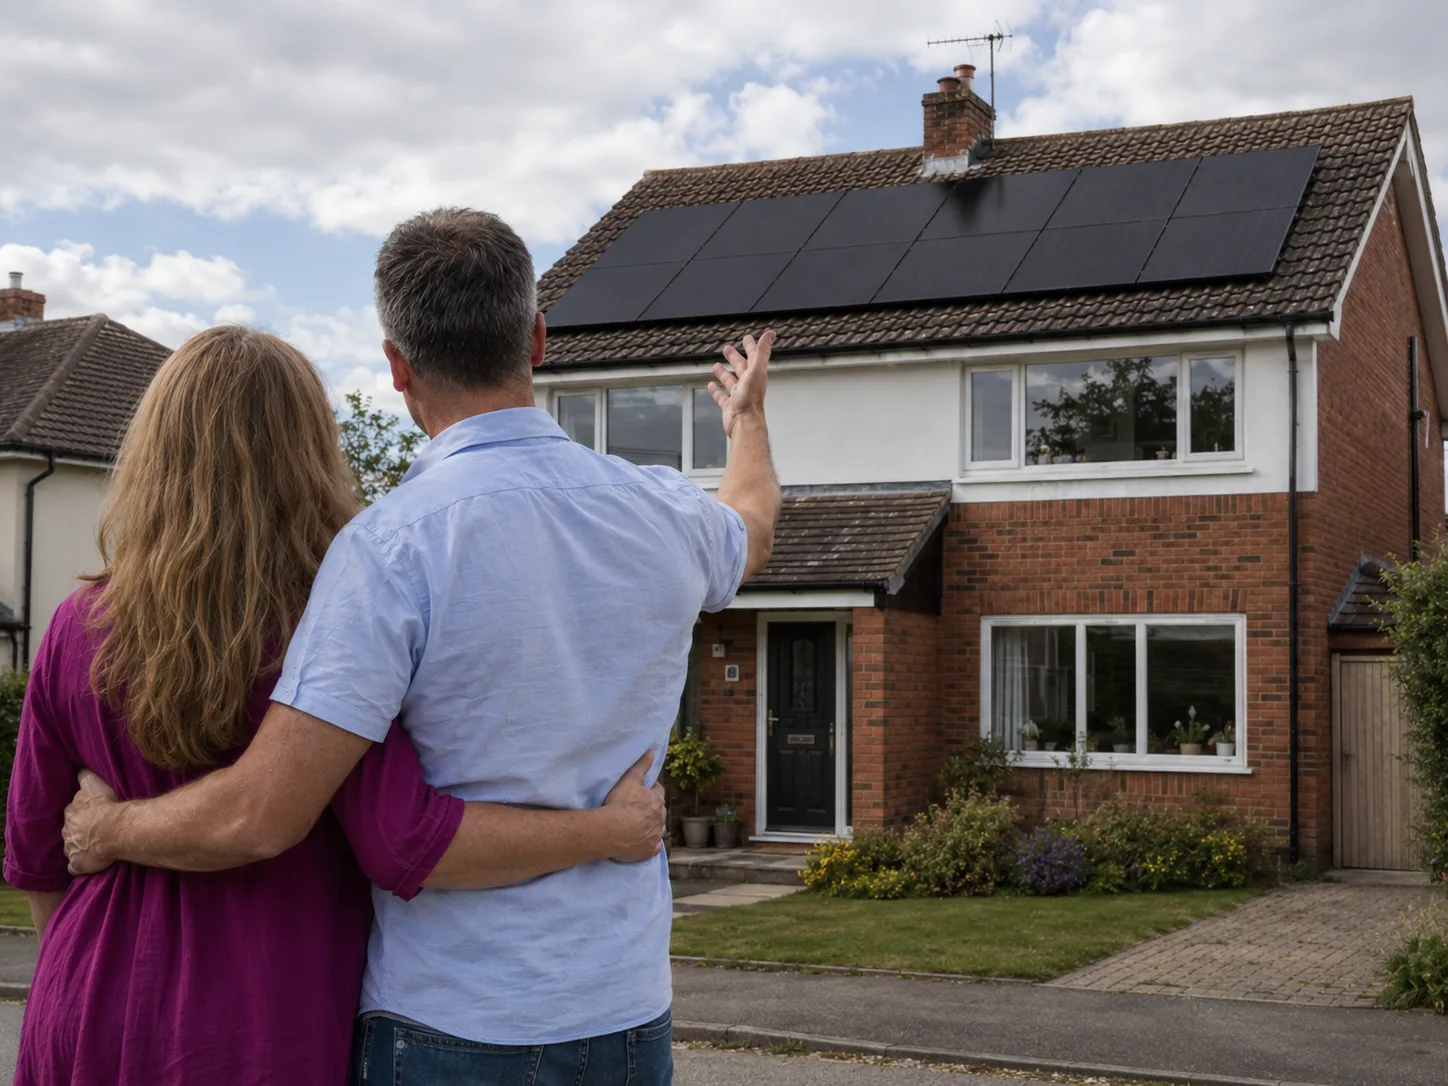
A Warm Homes Loan for solar panels, a home battery or both can be arranged under the Warm Homes Loan Scheme, with a separate limit of £15,000 for each. These are separate maximums, not one flexible £30,000 allowance, and the amount available depends on eligible costs and lender approval. The rate is government-supported, so it can be lower than a lender's usual rate. The installer must hold the relevant MCS certification for the technology being installed, and the lender decides whether to approve you.
Solar panels, a battery, or both?
You can borrow for solar panels on their own, a battery on its own, or a solar and battery installation together. Each measure has its own limit, so we itemise the cost of each part to show how the limits apply to your system.
Why people pair solar with a battery
Solar makes electricity while the sun is up, and a battery lets you keep some of it for the evening. A compatible battery can also charge from the grid when electricity is cheaper and supply the home during more expensive periods. We assess whether that suits your usage and tariff alongside the solar design. Savings are estimates and depend on your home, so we model your own figures during your free quote.
One of our Kent installations combines 5 kWp of solar with 11.52 kWh of storage. The panels generate electricity during daylight hours, and the battery gives the household more flexibility over when that energy is used. The right balance for your home depends on how much electricity you use and when you use it.
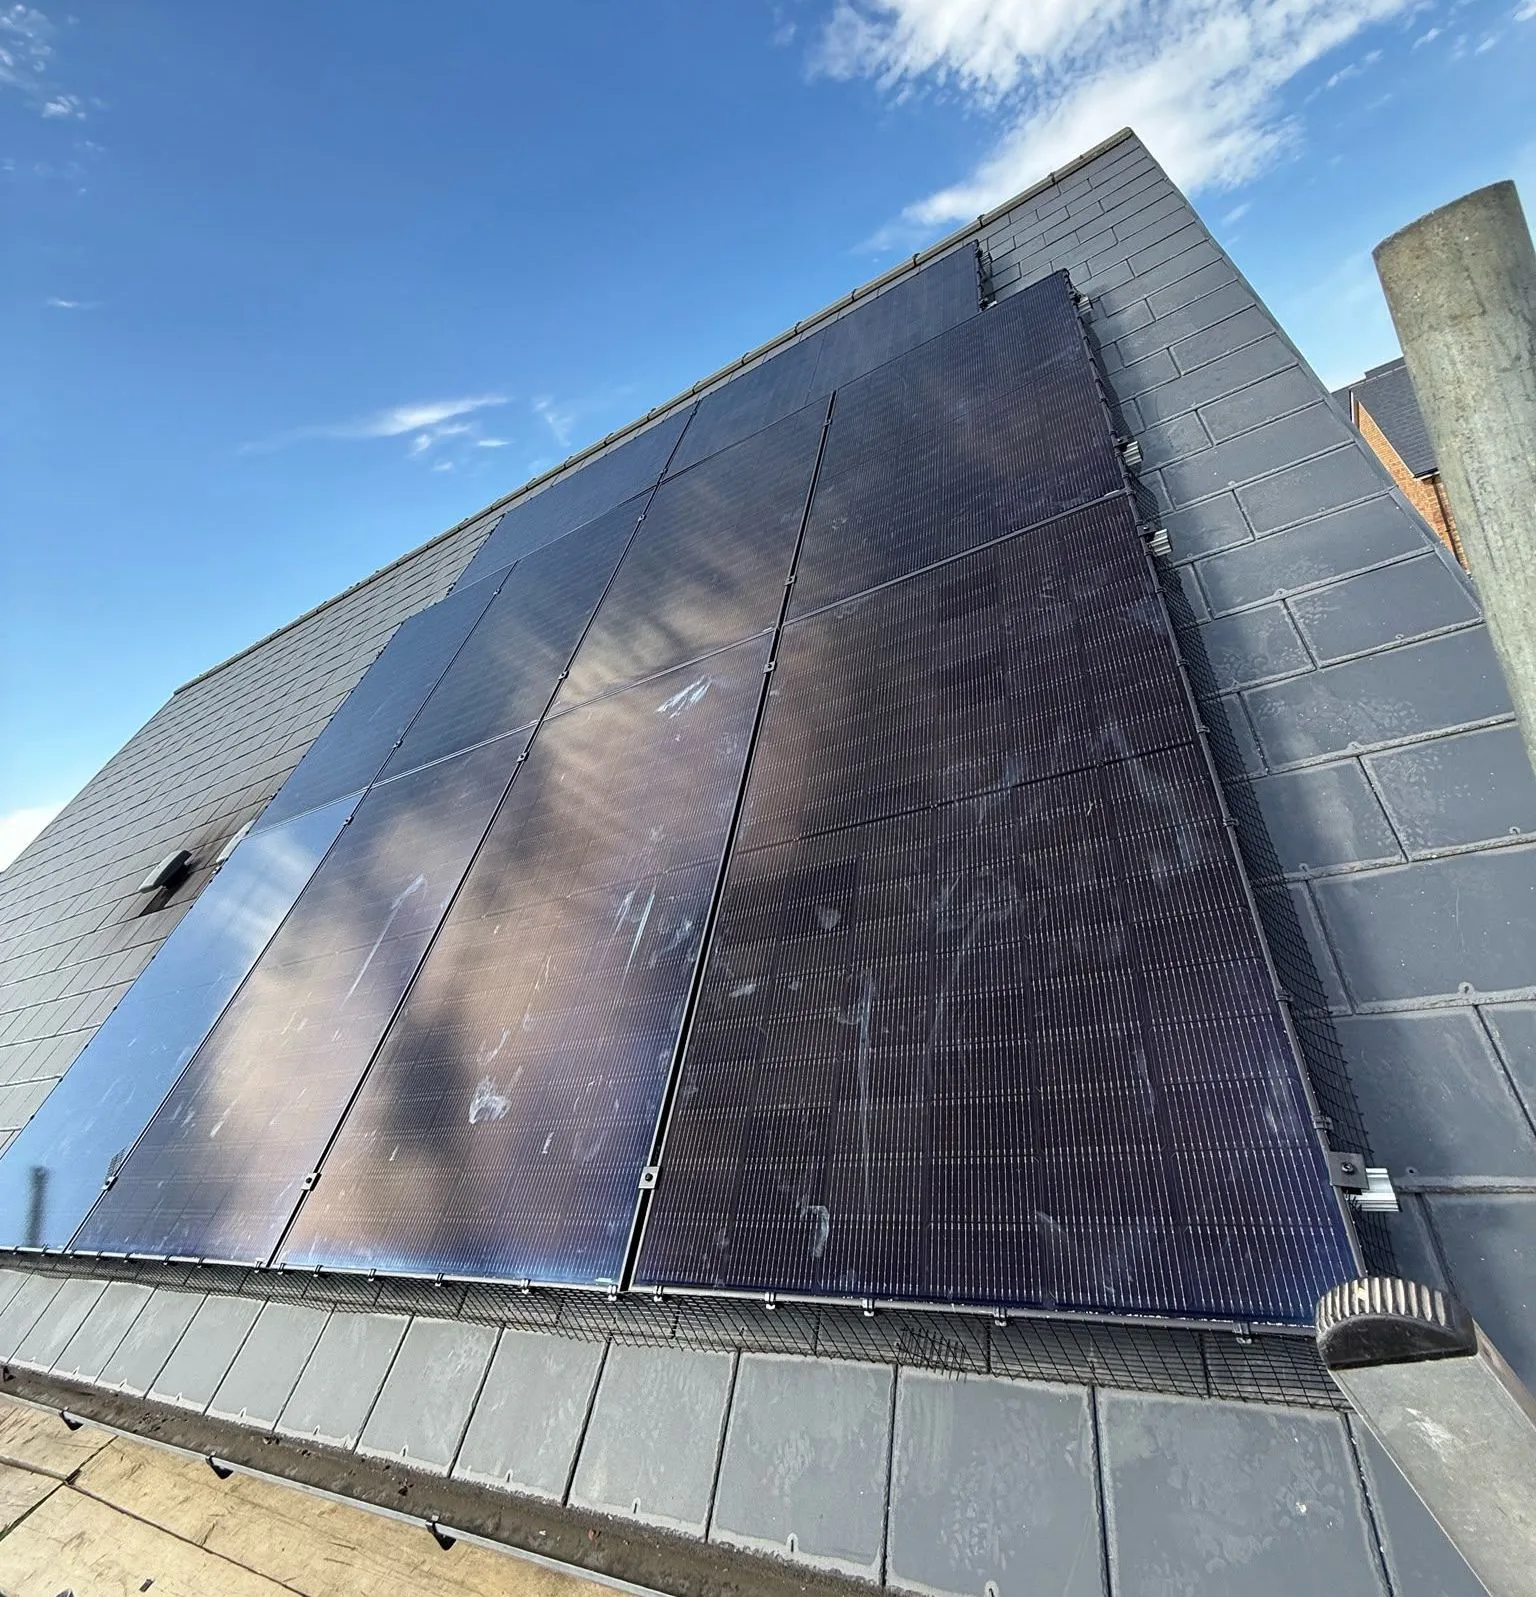 Kent10 panels, 5 kWp, with an 11.52 kWh batteryEstimated first-year benefit £1,771See our Kent installs
This illustrates a REST UK installation, not necessarily a customer who used this loan scheme. The forecast combines solar savings, export income and cheaper overnight battery charging for the complete system. It is an estimate, not a typical result or a guarantee, and it does not deduct loan repayments.
What if my system costs more than the limit?
If the eligible cost exceeds the scheme-supported limit, the excess must be covered separately. Your lender may also require an upfront contribution. We itemise the work and explain what can be included, what must be paid separately and when each payment is due.
A measure that costs more than its limit
Here is how the separate limits work. A project with £17,000 of eligible solar costs and £8,000 of eligible battery costs would exceed the solar limit by £2,000, even though the total is below £30,000. The unused battery allowance cannot automatically be transferred to the panels. This is an illustration of separate limits, not a REST price or offer, and we explain the route your lender supports for any excess.
What is included in the loan?
The loan can cover the installation work and the necessary extras for each measure, such as access equipment, the grid connection, inverters and isolators for solar, and the integration and controls for a battery. The scheme also covers heat pumps and some other technologies, each with its own limit on GOV.UK. This guide stays with solar panels and batteries, which are the measures we install.
Part of the loan
- Solar panels and the work to fit them
- A home battery, with or without solar
- An EV charger installed as part of your solar or battery system, within the limit
- Necessary extras for each measure, within its limit
Quoted separately
- Insulation, roofing or structural work
- An EV charger on its own, because the scheme only covers one fitted with solar or a battery
- Work for a business or a limited company, because the loan is for individuals
The chargepoint and its installer must meet the scheme's OZEV approval requirements. A charger already supported by an OZEV or other grant cannot have the same installation costs financed again under this scheme.
Already have solar panels?
What the lender looks at
The lender makes its own decision. It runs credit and affordability checks and considers your existing commitments, as it would for any application. An existing mortgage does not rule you out. We explain what to expect before you apply, and we help you complete the application.
What happens once you accept
Your lender sets out the rate, repayments and any conditions before you accept the loan. Once the necessary approvals and paperwork are in place, we arrange the installation and provide the completion documents. The lender uses the required installation evidence to verify scheme eligibility. We explain the payment and certification steps that apply to your product.
Questions to ask any lender
- What is the APR for my term, and what is the total amount repayable?
- Are there any fees?
- Can I overpay or settle early, and is there a charge?
- Does my project, including the battery, qualify?
For the bigger picture, start with our Warm Homes Loan Scheme guide, compare the main ways to pay in our solar panel finance guide and see where to find supply details in our MPAN guide.
Why homeowners choose REST UK
Finance is subject to status and lender approval. REST UK is a credit broker, not a lender (FCA 824643), and introduces customers to its lending partners. We do not give mortgage or whole-market financial advice. We may receive commission from the lender for introducing finance. Rates and terms are set by the lender and may change.